
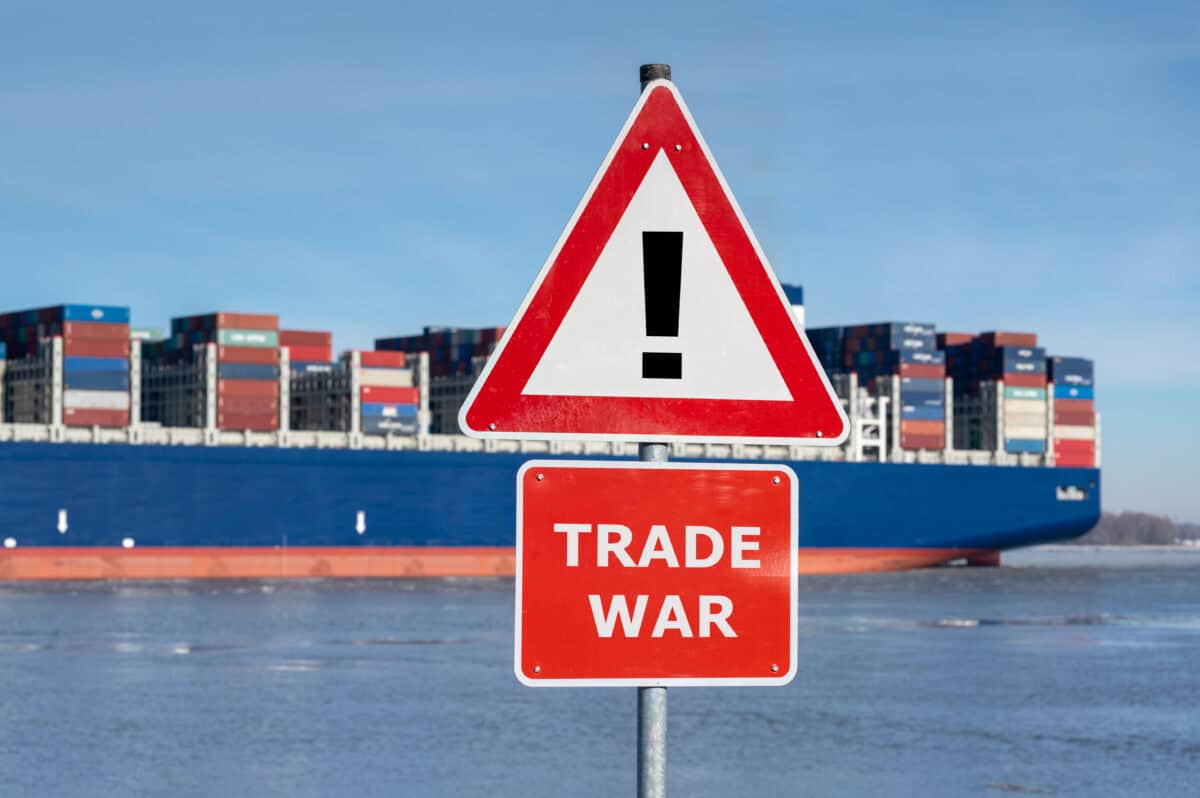
Tariff news can make an auto-parts stock look either doomed or rescued before anyone has checked which shipment the rule actually covers. The paperwork is less exciting than the headline, but does a much better job of predicting the bill.
Under the U.S. framework described in the trade representative’s 2026 automotive report, qualifying USMCA auto parts receive different treatment from non-qualifying imports under the relevant parts tariff. Eligibility depends on the product and the applicable origin rules. A company doesn’t receive a lifetime tariff-free membership because its headquarters happen to be in Canada.
Investors therefore need to connect trade rules with factories, customers, and individual supply chains. A supplier can have qualifying shipments alongside other exposure, including tariffs affecting materials or its customers. That makes a blanket statement that an entire stock already qualifies far too broad.
Source: Getty Images
Local production can help
Auto manufacturers value suppliers that can serve regional assembly plants reliably. Manufacturing near customers may reduce some border exposure and transportation complications, although every location also brings labour, tooling, and operating costs. Moving production isn’t as simple as changing the delivery address on an online order.
Magna International (TSX: MG) has a global manufacturing network and relationships with major vehicle producers. That scale gives it options for serving customers across markets. It also means the business is exposed to several economies and more than one set of trade rules.
The strongest investment case doesn’t require every tariff problem to disappear. It requires Magna to manage its contracts and operations well enough that more of its sales become cash for shareholders, even while customers adjust production plans.
The margin offers some evidence
Magna’s second-quarter sales rose 3% to US$11 billion. Its adjusted earnings before interest and taxes margin improved to 6.2%, up 0.7 percentage points from a year earlier.
That margin improvement is useful because revenue growth alone doesn’t show whether a supplier is earning enough on each programme. Cost recovery, manufacturing efficiency, and the product mix can be more important than winning work that carries disappointing returns.
The figures also need to survive a less helpful quarter. New program launches can be expensive, vehicle production can be cut, and a customer may ask suppliers to share the financial pain. An encouraging result gives investors evidence of progress, not immunity from the industry’s next slowdown.
Into earnings
Magna closed recently at $92.34 in Toronto. Against quarterly adjusted earnings per share (EPS) of US$1.86, that is about 8.8 times earnings. If that earnings pace were 25% lower, the multiple would rise to about 11.7 at the same U.S. price. That leaves some valuation appeal, provided the recent margin improvement lasts. Capital spending remains a competing claim on cash. Investors researching Canadian stocks shouldn’t treat a low-looking multiple from a strong quarter as evidence that tariff risk has already been fully priced in.
For a dividend portfolio, Magna could offer cyclical exposure alongside more predictable holdings. I’d keep its position smaller than the excitement around one trade announcement might suggest. A factory network can create an advantage without guaranteeing a smooth earnings path.
A lower purchase multiple also leaves room for disappointment without making the shares automatically safe. Auto suppliers can lose earnings quickly when production schedules change, especially after investing in equipment for a particular programme. I see Magna as a small value-oriented position for investors willing to hold through that cycle. Investors whose main goal is predictable household income have less reason to accept the same volatility.
Bottom line
My next checkpoint would be continued margin improvement and cash generation after investment. Those results would show that Magna is adapting commercially, not merely benefiting from a favourable interpretation of a tariff headline. That is the progress I’d want to own through the industry’s next round of rule changes.
Tariff news can make an auto-parts stock look either doomed or rescued before anyone has checked which shipment the rule actually covers. The paperwork is less exciting than the headline, but does a much better job of predicting the bill.
Under the U.S. framework described in the trade representative’s 2026 automotive report, qualifying USMCA auto parts receive different treatment from non-qualifying imports under the relevant parts tariff. Eligibility depends on the product and the applicable origin rules. A company doesn’t receive a lifetime tariff-free membership because its headquarters happen to be in Canada.
Investors therefore need to connect trade rules with factories, customers, and individual supply chains. A supplier can have qualifying shipments alongside other exposure, including tariffs affecting materials or its customers. That makes a blanket statement that an entire stock already qualifies far too broad.
Source: Getty Images
Local production can help
Auto manufacturers value suppliers that can serve regional assembly plants reliably. Manufacturing near customers may reduce some border exposure and transportation complications, although every location also brings labour, tooling, and operating costs. Moving production isn’t as simple as changing the delivery address on an online order.
Magna International (TSX: MG) has a global manufacturing network and relationships with major vehicle producers. That scale gives it options for serving customers across markets. It also means the business is exposed to several economies and more than one set of trade rules.
The strongest investment case doesn’t require every tariff problem to disappear. It requires Magna to manage its contracts and operations well enough that more of its sales become cash for shareholders, even while customers adjust production plans.
The margin offers some evidence
Magna’s second-quarter sales rose 3% to US$11 billion. Its adjusted earnings before interest and taxes margin improved to 6.2%, up 0.7 percentage points from a year earlier.
That margin improvement is useful because revenue growth alone doesn’t show whether a supplier is earning enough on each programme. Cost recovery, manufacturing efficiency, and the product mix can be more important than winning work that carries disappointing returns.
The figures also need to survive a less helpful quarter. New program launches can be expensive, vehicle production can be cut, and a customer may ask suppliers to share the financial pain. An encouraging result gives investors evidence of progress, not immunity from the industry’s next slowdown.
Into earnings
Magna closed recently at $92.34 in Toronto. Against quarterly adjusted earnings per share (EPS) of US$1.86, that is about 8.8 times earnings. If that earnings pace were 25% lower, the multiple would rise to about 11.7 at the same U.S. price. That leaves some valuation appeal, provided the recent margin improvement lasts. Capital spending remains a competing claim on cash. Investors researching Canadian stocks shouldn’t treat a low-looking multiple from a strong quarter as evidence that tariff risk has already been fully priced in.
For a dividend portfolio, Magna could offer cyclical exposure alongside more predictable holdings. I’d keep its position smaller than the excitement around one trade announcement might suggest. A factory network can create an advantage without guaranteeing a smooth earnings path.
A lower purchase multiple also leaves room for disappointment without making the shares automatically safe. Auto suppliers can lose earnings quickly when production schedules change, especially after investing in equipment for a particular programme. I see Magna as a small value-oriented position for investors willing to hold through that cycle. Investors whose main goal is predictable household income have less reason to accept the same volatility.
Bottom line
My next checkpoint would be continued margin improvement and cash generation after investment. Those results would show that Magna is adapting commercially, not merely benefiting from a favourable interpretation of a tariff headline. That is the progress I’d want to own through the industry’s next round of rule changes.